Licensed public adjusters & insurance appraisers
Their adjuster represents the carrier. We represent you.
The insurance adjuster who came out to your property represents your insurance company. That is their job, and they write the estimate your check comes from.
You deserve someone in your corner too. We are licensed public adjusters and insurance appraisers who represent the homeowner, and we are here to walk you through every step of the insurance process — so you can focus on your family and your home.
- We read your policy and tell you what it actually covers
- We inspect and document the damage before anything is torn out
- We write the estimate the repair really takes
- We deal with the carrier, the calls, and the paperwork
Free policy and claim review
Send us what happened. We will read your policy, look at your damage, and tell you plainly where your claim stands and whether you need us. No charge, no obligation.
Or call 504-644-3249. Your information is used only to respond to you.
Sound familiar?
Almost every call starts with one of these three sentences.
If you have said one of them out loud this week, we would be glad to help.
My claim was denied.
A denial is a position, not a verdict. Most of the denials we reopen came down to missing documentation or a disagreement about what caused the damage — not about whether you were covered.
They said it’s wear and tear.
Three words that close more claims than anything else in this business. Real storm damage gets written off as age all the time, and it takes a close-up, photographed inspection to prove otherwise.
I don’t understand my own policy.
Almost nobody does until they need it. There are separate deductibles, exclusions, time limits, and coverages you are owed and never claimed. We will read it with you for free.
Denied claims
A denial letter is a starting point, not the end of your claim.
Your insurance company made a decision based on one inspection, a handful of photos, and whatever documentation existed at that moment. That is all a denial is. It can be revisited, and it regularly is, when better evidence shows up.
Here is what we usually find behind a denied claim:
- The damage was never fully inspected — nobody got on the roof or into the attic
- The cause of loss was assigned wrong, so a covered loss was treated as an uncovered one
- Wind and water were never separated, so neither one got paid
- Documentation the carrier needed was never requested, or was sent and never logged
Send us the denial letter and your policy. We will tell you within days whether there is something real to pursue, and we will tell you if there is not.
Have my denial reviewed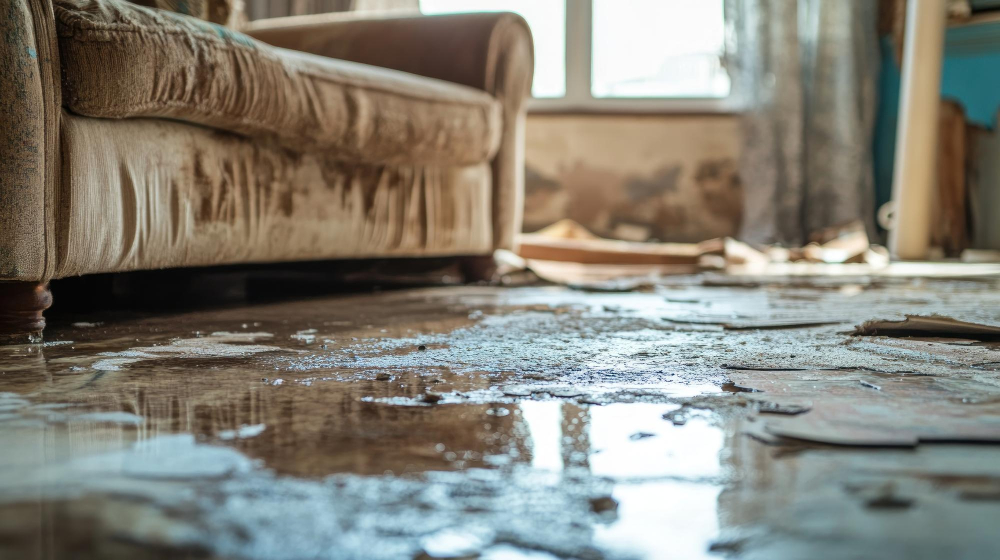
“Wear and tear”
The most expensive three words that can land in your file.
Storm damage does not always look dramatic from the driveway. Shingles get lifted by wind and settle back down. Seal lines break. Flashing pulls loose. Hail bruises the mat under the granules and leaves almost nothing to see. From the ground, all of it looks like an older roof — and that is how it gets written up.
We come from commercial and residential construction, so we inspect the way a contractor does before quoting the repair:
- On the roof, slope by slope, in test squares, with impacts counted and photographed
- Broken seals and creased tabs recorded up close — damage that is invisible from below
- Soft metals, vents, screens, siding, and gutters checked, because they date a storm
- Weather data matched to your loss date, so “that’s old damage” has an answer
Then we write it up so the damage is described as damage, in language and detail a carrier has to respond to.
Get a second look at my roof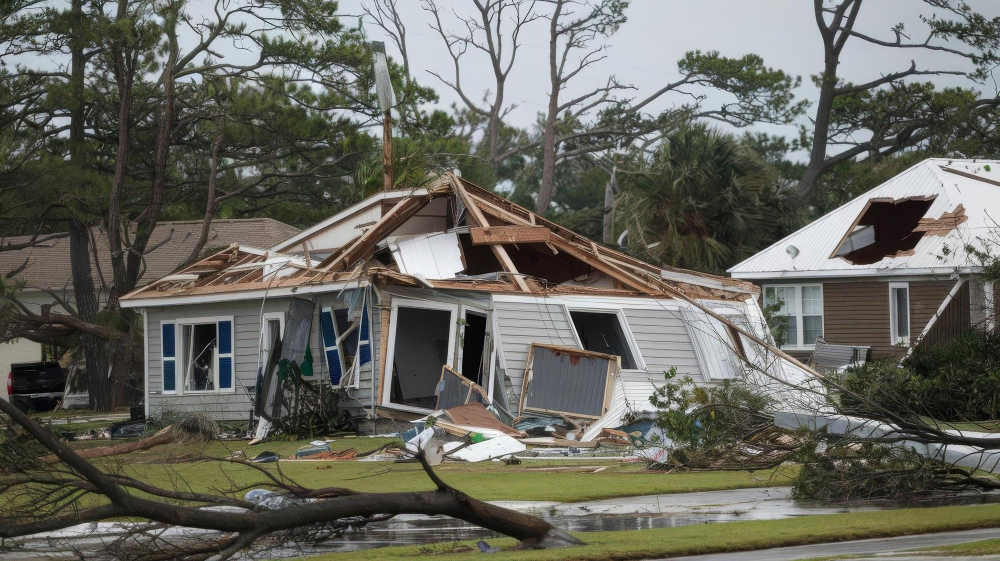
Free, before you owe us anything
We will read your policy and tell you what it actually says.
Most people meet their policy for the first time on the worst week of their year. Send it to us and we will go through it line by line, then tell you in plain language what you have — and whether you even need a public adjuster for this loss. Sometimes the answer is no, and we will say so.
- What is covered, and what is excluded
- Every deductible that applies, including separate hurricane and wind deductibles
- Coverage for somewhere to live while repairs happen
- What the policy requires you to do after a loss, and by when
- The deadlines that could bar your claim if you wait
- An honest answer on whether hiring us makes sense
Why you need your own
If the insurance company has an adjuster, you need one too.
Nobody would expect you to handle the other side’s paperwork in any other situation. A claim is no different.
The carrier’s adjuster
- Represents your insurance company
- Writes the estimate your settlement is based on
- Decides what goes in that estimate and what does not
- Handling hundreds of files at once after a storm
- Owes you a fair adjustment, but represents the carrier
Your adjuster — us
Licensed to represent you and paid by you
- Represents you, the homeowner, and only you
- Inspects the whole property up close, before cleanup
- Writes a line-by-line estimate priced for the real repair
- Takes the carrier’s calls, requests, and re-inspections
- You see every number and approve the result before anything is signed
Who you are calling
We built first. Then we adjusted claims. Now we are here for you.
Licensed public adjusters in Louisiana, Texas, Mississippi, Florida, North Carolina, Oklahoma, California, and Hawaii. We also serve as insurance appraisers when a claim goes to appraisal. Based in Belle Chasse, Louisiana. IICRC certified in Water Damage Restoration (WRT), Fire and Smoke Restoration (FSRT), and Applied Microbial Remediation (AMRT). Member, Louisiana Association of Public Adjusters.
Start here
Tell us what happened. We will tell you where you stand.
Send photos, your policy if you can find it, and any letter your insurer sent. If the loss just happened, photograph everything before cleanup starts, keep your receipts, and make only the temporary repairs that stop further damage.
Then call us. The review is free, and you will get a straight answer either way.
Call now504-644-3249Free policy and claim review
Two minutes now, and somebody who does this every day reads your policy and your claim.
Or call 504-644-3249.